
When it comes to finances, I always have the best intentions of finally getting things together. Every New Year’s resolutions list, fall reset checklist, and monthly goals manifestation has some variation of “make a finance plan” right at the top. But every time I sit down to do it, I honestly have no idea where to start, and that early decision paralysis keeps me from making any meaningful progress. The good news? Getting better with money doesn’t have to mean overhauling your entire life—or becoming a spreadsheet person.
At The Everygirl’s recent Financial Glow-Up: Building Wealth Without Burnout event with Bank of America, The Everygirl Podcast host Josie Santi sat down with Holly O’Neill, President of Consumer, Retail and Preferred Banking at Bank of America, for a conversation about making financial wellness feel more approachable and actually doable. From figuring out where your money is going to spending on the things you genuinely enjoy, here are eight simple ways to give your finances a glow-up without burning yourself out.
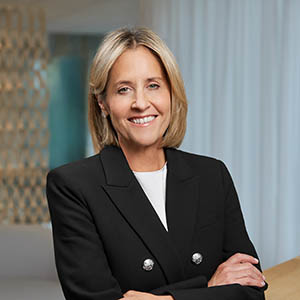
Holly O’Neill
Holly O’Neill is president of Consumer, Retail and Preferred Banking at Bank of America and a member of the company’s executive management team. She leads Retail Banking and Preferred Banking, serving the financial needs of 69 million clients. O’Neill has been recognized by Barron’s as one of the 100 Most Influential Women in U.S. Finance for five consecutive years and by American Banker as one of the Most Powerful Women in Banking.
1. Start by figuring out where your money is going
My problem with budgeting has always been that I have no clue how much to allocate to each category. How do I know what I need for groceries when I just tap and pray at the Trader Joe’s checkout? Turning a blind eye may feel less stressful when it comes to finances, but it’s really the root of all of your problems.
Before you can even create a budget, you need to know how much money is coming in and how much money is going out. Thankfully, mobile banking apps make this so simple. Take a look at your past month’s purchases (the good, the bad, and the ugly), and see exactly where you’re spending your money before sitting down and figuring out where you actually want that money to go.
The takeaway: You don’t have to create the perfect budget on day one. Start by getting an honest picture of your current spending.
2. Try the 50/30/20 rule
If budget has always been synonymous with constraint in your mind, it’s time to redefine what a budget is. Budgets don’t mean never spending money on your wants; it just means you’re spending your money in a way that serves your current and future financial goals. O’Neill recommends following the 50/30/20 rule as a starting point.
Fifty percent of your income should go to your needs. This includes rent, groceries, car payments, Wi-Fi bills, etc. Thirty percent goes toward your wants. Yes, you read that right: financial wellness isn’t about never spending money on you. That’s part of living well! This category includes entertainment, shopping, and your go-to takeout spot you look forward to ordering from every Friday. Lastly, set aside 20 percent of your income for savings and long-term financial goals.
A good rule of thumb: Think of 50/30/20 as a starting point, not a rigid requirement. Your percentages may look different depending on your income, expenses, and goals.
3. Split that 20% with intention
Okay, so we’re supposed to put aside 20 percent of our income for savings…Where? How? Why? I’ve had all these questions rapid-fire in my brain the second someone brings up the elusive “savings.” But don’t worry, Holly O’Neill broke down exactly what this 20 percent should look like, and it’s honestly much easier than I know I’ve been building it up in my head.
Start with an emergency fund
“Saving” can look like a few different things. As a kid, it was probably a piggy bank you used to save up for a new American Girl doll, but as an adult, there are plenty of tools to ensure your money builds wealth on its own. The very first savings account to build out is an emergency fund. Typically, this looks like six months of living expenses sitting in a high-yield savings account, so when, inevitably, any unexpected costs, like a medical bill or broken appliance, pop up, your budget isn’t completely derailed. And because it’s in a high-yield savings account, it pays a much higher interest rate than a traditional savings account.
Then, think about retirement
Once your emergency fund is built out, it’s in your best interest to start putting savings into long-term retirement accounts like a 401(k). This money will sit and build interest until you turn 60. So while it isn’t readily accessible, it’s building long-term wealth for you later in life, a huge part of financial wellness. A good place to start is contributing, at the very minimum, what your company will match to a 401(k) account. That way, you’re capitalizing on your benefits and not missing out on any free money.
If your budget allows, the best move is to max out your 401(k) account. Once you’ve maxed out your 401(k), you can start building up other tax-advantaged retirement accounts like a Roth IRA and even open non-retirement investment accounts.
4. Leave room for fun in your budget
If you’ve been gaslit into thinking that your $7 latte once a week is why you can’t afford to buy a house, you’re not alone. But we can thank Holly for finally validating that your little sweet treat isn’t the downfall of your financial well-being. In fact, she thinks treats are an integral part of healthy financial habits.
The key is to only treat yourself within the parameters your “wants” category in your budget allows. It’s likely that a fun drink on your way to work every Friday is completely within reason, and you should toss any guilt out the door. But every day? Your at-home latte is probably a far cheaper way to get your caffeine fix. So, don’t cut out treats during your financial glow-up; just make sure you’re doing it smartly.
The takeaway: A sustainable budget should account for the things that make your life enjoyable—not just your bills.
5. Give yourself a 24-hour pause before big purchases
We have all fallen victim to the ill-fated impulse purchase. That on-sale Anthro dress you were convinced by your Instagram ads that you absolutely needed, only for it to collect dust until the perfect excuse to wear it finally pops up. We’ve all been there. And while impulsive purchases aren’t completely avoidable, the 24-hour rule ensures they’re not a common occurrence in your financial habits.
If you find yourself scrolling online and coming across something you absolutely have to have, just sit on it for 24 hours. If you’re still desperate for it, add it to your cart! But chances are, the luster will have dulled, and you’ll realize you don’t actually even want whatever it is that seemed like such a must-have the day before.
6. Keep your long-term goals in mind when you spend
The key to prioritizing financial wellness is always keeping long-term goals at the forefront. Yeah, a new phone sounds nice, but when held against the satisfaction of finally buying a house, taking a luxury vacation, or investing in a passion project, you realize you’d rather put that money toward your goals. So, when considering whether an investment like a new work bag or upgraded laptop isn’t just a waste of money, evaluate it in terms of your long-term goals.
Will this purchase bring you one step closer to your financial goals? How often will you use it? Or is it something you kind of want but not badly enough to budget for? When you know what you’re working toward, it becomes much clearer whether purchases are worth it.
Before you buy, ask yourself: What am I choosing this purchase instead of? Sometimes, knowing what you’re working toward makes the answer pretty clear.
7. Make the most of the financial benefits you already have
Savings and investment accounts aren’t the only way to ensure your money is working for you. If you have a credit card, bank account, or rewards program, take a few minutes to figure out what benefits you’re already entitled to. Whether it’s travel points, hotel upgrades, cash back, or other perks, make sure you’re actually using the benefits that come with the financial products you already have.
At our Financial Glow-Up event, O’Neill also highlighted BofA Rewards, which gives eligible Bank of America clients opportunities to earn rewards. The bigger takeaway? A financial glow-up isn’t always about adding something new to your life. Sometimes, it’s about getting more value from what you’re already using. The BoA app makes it easy to see your rewards and take advantage of them, so you’re not leaving benefits on the table.
8. Remember: progress over perfection
The biggest takeaway from Josie and Holly’s conversation is that progress is so much more important than perfection. Try as we might, there will be months where you veer off budget or end up with an impulse purchase you wish you could return, but what matters isn’t the mistake; it’s getting back on track. Instead of waiting for the moment to feel perfect, start practicing financial wellness today. Even taking the first step is a huge win.
You don’t need to become a personal-finance expert overnight. You don’t need a perfect budget, a six-figure salary, or a color-coded spreadsheet. The goal is simply to understand your money a little better, make a few intentional changes, and keep going.
That was ultimately the biggest takeaway from Josie and Holly’s conversation: financial wellness isn’t about getting everything right. It’s about giving your future self more options, one decision at a time.
Looking for more financial glow-up advice?
If you want to hear the full conversation that inspired these tips, watch Josie and Holly’s conversation from The Everygirl’s Financial Glow-Up: Building Wealth Without Burnout event below. They get into everything from budgeting and saving to spending without guilt—and how to make building wealth feel a little less overwhelming.
Prefer to listen? You can also hear Josie and Holly continue the conversation on The Everygirl Podcast, where they dive even deeper into building financial confidence and healthier money habits.
LISTEN NOW: Financial Glow-Up—Girl’s Guide to Building Wealth Without Burnout
Lauren Blue, Editor & Book Club Co-Host
As an Editor for The Everygirl, Lauren ideates and writes content for every facet of our readers’ lives, from must-read books and behind-the-scenes interviews to beauty products she can’t live without. When she isn’t sitting in an AMC watching the latest buzzy release, she can be found scouring Goodreads for the perfect pick for The Everygirl Book Club. There, she co-hosts discussions with members, debating plotlines, fancasting characters, and, of course, tossing in her own recommendations.
This post is sponsored by Bank of America but all of the opinions within are those of The Everygirl editorial board.
The post 8 Simple Ways to Have a Financial Glow-Up (No Spreadsheet Required) appeared first on The Everygirl.